Showing posts with label Keyes Company. Show all posts

Friday, March 1, 2019

We Are Unable to Offer You The Property

Protecting Yourself and Your Rental Property

Benjamin Gene is the President of KPM,
and has over a decade of industry experience

Rising property values and a smaller inventory of affordable starter homes have led to a boom in the rental market. Few places can boast as strong a market as South Florida, where great rental opportunities get filled as quickly as they come up for rent.

This has led to a situation where landlords or agents get themselves into trouble with Fair Housing Practices in the way that they turn down prospective rental applicants. Today's guest post comes from Benjamin Gene, President of Keyes Property Management with a word of advice on how to do this and make sure you don't open yourself up to potential liability.


I’d like to discuss declining tenants for a rental. As some of us have seen, there are now “Professional Tenants” who will call around to speak with agents or owners of rental listings to try and trip them up on Fair Housing issues before suing them for breach of those laws.

What I would like to do today is tell you how to legally decline a prospective tenant. It’s actually very simple. Simply state, “I’m sorry. We are not able to offer you the property at this time.” No matter their response, including when they ask why, repeat the phrase again.

This way, you don’t open up any avenues to allow them to claim that you violated any Fair Housing laws. They may get frustrated at your insistence on repeating that phrase, but it will protect you or the owners from violations.

Additionally, at MyRentalScreening.com, KPM will provide owners and agents with a summary page of why a tenant has been declined. This is based on criteria that they agree to prior to filling out the application. The only reason you must put in writing why you decline a tenant is for credit reasons. You do this by providing an Adverse Action letter. At MyRentalScreening.com, we provide you with this letter. Remember, the only thing to say is, “I’m sorry. We are not able to offer you the property at this time.”

Friday, February 22, 2019

Borrowing Against the American Dream

Student Loan Debt & Its Effect on Mortgage Lending

Craig Garcia, President
Capital Partners Mortgage
Through the second quarter of last year, student loan debt lagged behind only mortgages as the largest consumer debt segment in the United States. And while mortgage debt has remained steady, with negligible growth over the last 10 years, student loan debt continues to skyrocket. 

That growth in outstanding student loan debt has ripple effects across the nation's economy, as younger generations see much of their spending power go to monthly payments on this debt. In turn, that keeps many from feeling like they can take the step of buying a house. Today's guest post comes from Craig Garcia, who gives a glimmer of hope, along with some advice, for anyone who still wants that piece of the American Dream that is homeownership.


I’d like to talk to you about student loans. A recent Federal Reserve study showed that student loan debt has become a major hurdle for younger generations looking to buy a home. Being in the mortgage lending business, and seeing what we see on a regular basis, I wholeheartedly agree. Most of you out there with student loans might say something like, “yes, we already knew that.”

What you might not understand is that one of the main obstacles actually stems from the mortgage loan industry itself. Loan programs are challenging. It’s why you shouldn’t just go and apply for a mortgage on your phone or without putting some thought into it. 

The four most common loan programs available to potential buyers all treat student loan debt and payments differently. That sets the stage for confusion. Let me break down some options available to those consumers with student loan debt, because our job is to help as many people as are able to successfully complete the home buying process!

1.     VA Loans – If your student loan payments could be deferred for up to a year after closing, then the VA will then be able to state that they won’t count any student loan payments against you when it comes to qualifying for a mortgage loan as a Veteran.
2.     Fannie Mae & Income-based Student Loan Repayment Plans – Your student loan lender has options to base your student loan payment on your income, temporarily offering you relief with lower, more manageable payment terms. The most aggressive loan program that will accept that lower payment when it comes to qualifying you for a loan is Fannie Mae’s conventional loan program. They will look at your new payment terms and accept those when determining your eligibility for a mortgage loan.

It’s important to remember that, in these circumstances, you will still need to be able to cover a mortgage payment and student loan payment eventually. Make sure you plan for those expenses and know that you will be able to successfully pay them.

It’s an unfortunate fact right now that student loan debt has become a large obstacle when it comes to purchasing a house, but it hasn’t made it impossible. If you feel that homeownership is the next step in your life, come talk to us at Capital Partners Mortgage today, and we can offer you advice and guidance as to how you can achieve this goal!

- Craig Garcia, President | Capital Partners Mortgage

www.capitalpartnersmtg.com

Wednesday, February 20, 2019

A Beginners Guide to Equity

Building Equity in Your Home

Your home is one of the best investments you'll ever make. Not only does it provide you and your family the security of an inflation-proof dwelling, but as your equity grows, it becomes a solid financial tool in building wealth. Understanding the basics of what equity is, how it grows and what you can do with it is the first step in using your home as an asset that grows in value.

What is Equity?

Simply put, equity is the difference between what your home is worth and how much you owe against that value. For example, if you own a home worth $500,000 and you currently owe $400,000 on your mortgage, your equity is $100,000. This is actually the amount of the home you own, and if you sold the home (minus costs related to its sale) would be the amount you receive from the sale.

Building Equity

Equity grows in one of several ways: the property value increases, you pay down the debt, or you add value to the home in some way.

The most common driver of property value increase comes from market demand. When interest rates are low and the economy is strong, more buyers enter the market and the demand for homes outpaces the amount of inventory, or homes for sale. This, in turn, causes a "seller's market." When this happens, the value of homes increases and equity rises along with it.

Paying down the debt owed on a home also adds to your equity. Some homeowners choose to make extra payments against the principal of their mortgage loan along with their monthly payment. Even an extra $500/month can add up over time, shorten the repayment length, decrease the total interest paid, and grow equity.

Renovations and home improvements can also add to the value of the home, thus increasing equity. Updated kitchens and bathrooms, adding extra square footage, remodeling the back yard or adding a pool can create more than a dollar-for-dollar increase in value. A well maintained, upgraded home will always command a higher sale price than its run-down counterpart.

Using Your Equity

Having equity in your home provides financial security. Not only does it provide peace of mind, it can be used, even without selling the property.
  • Borrow Against Your Equity - A second home loan, usually referred to as a HELOC or home equity line of credit, allows the homeowner to take some (or all) of the equity out of the home to use for investment, home improvement, or any number of other cases.
  • Receive Cash at Selling - Of course, the most obvious use of equity is to have money left over when you sell your home. This can be used to help with a down payment on a new home, for retirement spending, or to add to your savings.
Buying a property and building equity is one of the biggest advantages of homeownership. As rental rates continue to rise, a 30-year mortgage payment stays the same, protecting against inflation. With each payment, the borrower pays more principal and less interest. As the market appreciates and equity increases, the property provides an asset which not only provides the owners a home to enjoy, but a financial investment that continues to grow in value.

A Keyes Realtor is always available to answer your real estate questions. Call or come in to your local office today, or visit us at www.Keyes.com


Monday, July 23, 2018

Keyes Luxury Report Gives Insights into High End Markets in South Florida


From the Sun Sentinel 

The luxury market in South Florida is unique in many ways. The defining characteristics of this rarified set of properties have led to "what luxury real estate agents are happily calling one of South Florida's best price and sales surges in recent memory."

Leading the way in bringing this information to the public eye, The Keyes Company's Luxury Market Report demonstrated a few of the reasons for this boom - when other cities might not be undergoing the same increase in sales of their own high-end listings.

Check out insights into the mind of Keyes' Vice President of Luxury, Kevin Leonard, and why this trend might continue here.

http://www.sun-sentinel.com/business/fl-bz-south-florida-luxury-home-market-spikes-20180718-story.html#

Wednesday, February 14, 2018

Realtor Recommendations: Flipping homes? Condition Matters

By Lucy Ballesteros and Debbie Riano


The home flipping process can take any house and turn it into a dream sanctuary, but be careful! While a listing might look perfect on the outside, not every home condition is in tip-top shape. Before you sign on the dotted line, there are some things you should be on the lookout for. With these few tips, you’ll be a pro at your next walk through.


1. Underneath it all
When purchasing a flipped property you must be wary of any mold issues. Many flipped properties were at one point distressed properties and may have had water issues. The investor who picked up the property may or may not have tested for mold or might have just painted over it. Pay for a mold test for peace of mind.

2. Cover yourself
Check the roof, its age, any potential leaks, or paint overs. Replacing a roof is a huge investment and many investors will not want to put that much money into a replacement if it isn't absolutely necessary.  You can check with the city where the property is located for permits on how new a roof really is.

3. It’s electric
On older properties, the electrical and plumbing may not be up to code. Investors will not replace electrical panels or update plumbing connections unless there is a problem. Hiring a good company to perform an inspection is key to finding out all the details regarding your plumbing and electrical work on your property. You can use a well-researched inspection report to negotiate on the price of your soon to be property.

Remember, not all flipped homes have issues! Don’t be afraid to keep these options open when you’re shopping the market for a new home. For more flipped home advice, check out the article below, or give us a call at 561-713-8872.


Monday, October 23, 2017

Keyes Voted #1 Real Estate company in Port St. Lucie!

Hometown News Readers rank The Keyes Company as #1 in Port St. Lucie! 


The Keyes Company was recently voted #1 real estate company in Port St. Lucie by Hometown News readers. Thank you to each of our customers who gave us the opportunity to earn this award with incredible service. We would be remiss if we didn’t give our Realtors® the recognition they deserve as well. They are on the front lines each day, working with buyers and sellers  helping them navigate a complicated, tricky process. We want to say to each one of you a big  THANK YOU! #KeyesRealtors #KeyesCompany #PortStLucieRealEstate #Itsgoodtobenumber1

Friday, October 13, 2017

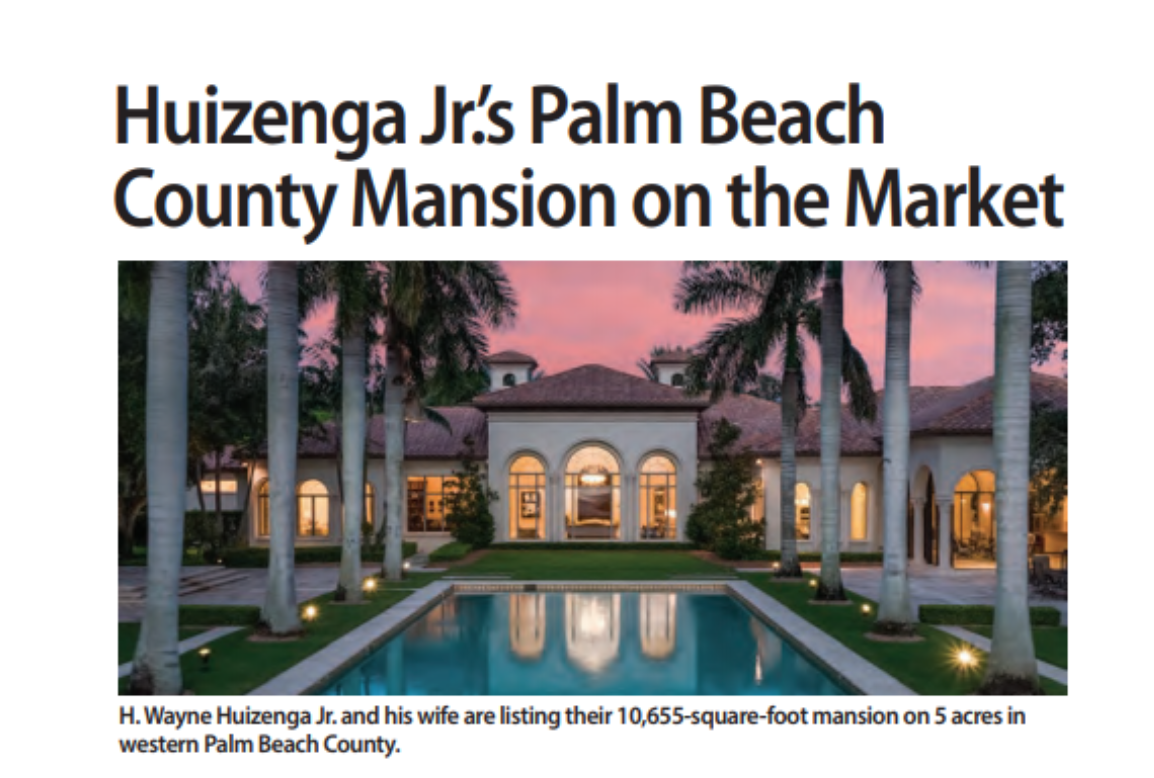
The Keyes Company's Nash Group lists H. Wayne Huizenga Jr. lakefront estate.

Stunning Delray Beach residence in the exclusive community, Stonecreek Ranch, enhances Billy Nash's continued dominance in luxury real estate.


Keyes Company's Billy Nash announced the listing of the Huizenga Jr.'s lakefront estate. The asking price for the property is currently set at $6,750,000.

The estate was built 10 years ago, and is on 5 acres of land. It features 7 bedrooms, 10 bathrooms, and a beautiful in-ground pool. The interior was recently renovated by Tim Ellis and Palm Beach luxury designer Annie Santulli of Santulli Designs.

"Billy Nash and his Nash Group are perfectly suited to market this one-of-a-kind home on behalf of the Huizenga family," said Keyes President and CEO Mike Pappas. Nash had earlier closed a $7.5 million sale of a compound at Jack Nicklaus' Bear's Club in Jupiter. 

Billy Nash
Over the last 18 months, Nash has surpassed the $25 million mark in transactions. He has spent nearly 25 years working with and advising ultra-high-net-worth individuals and their families. Nash describes the property as being perfect for hosting large private events or just simply enjoying the South Florida lifestyle with family and friends. "Our team will be generating interest in the property both locally and around the world," says Nash. 

On top of this, Nash is also in the process of marketing a $33 million compound in Key Biscayne for Michael Cohl, the former Chairman of Live Nation and touring manager of the Rolling Stones.